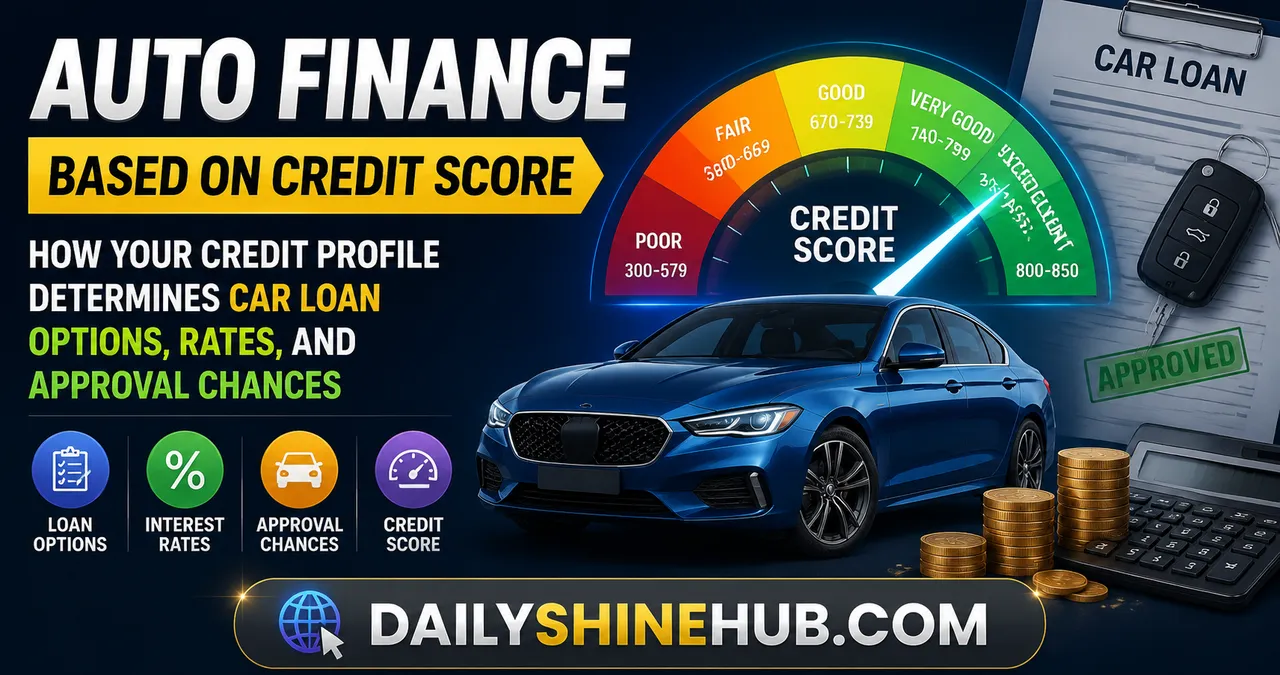
Buying a vehicle is one of the biggest financial decisions many people make, and for most buyers, auto finance is the bridge between wanting a car and owning one. However, not every borrower receives the same loan terms. The interest rate offered, loan amount approved, required down payment, and repayment flexibility often depend heavily on one factor: credit score.
For consumers trying to finance a new or used vehicle, understanding how credit scores influence auto finance can make the difference between an affordable loan and a costly financial burden. A strong credit profile can unlock lower interest rates and better lender offers, while a weaker score may lead to higher costs, stricter requirements, or limited financing options.
This guide is designed for car buyers who want to understand credit score-based auto finance, improve their borrowing position, and make smarter decisions before applying for a vehicle loan.
Understanding the Connection Between Credit Score and Auto Finance
A credit score is a numerical representation of a borrower’s credit history and financial reliability. Lenders use this score to estimate the likelihood that a person will repay borrowed money on time. When someone applies for auto finance, lenders typically review the credit score along with income, employment history, debt levels, and loan terms.
From a lender’s perspective, a higher credit score indicates lower risk. Borrowers with strong credit histories have usually demonstrated responsible payment behavior, manageable debt, and consistent financial habits. Because they represent less risk, lenders are often willing to offer them:
- Lower annual percentage rates (APRs)
- Larger loan approvals
- Smaller down payment requirements
- More flexible repayment options
- Access to promotional financing offers
On the other hand, applicants with lower credit scores may face higher interest rates because lenders compensate for the increased possibility of missed payments.
Why Credit Score Matters More Than Many Car Buyers Realize
Many buyers focus mainly on the vehicle price and monthly payment, but the interest rate determined by credit score can significantly change the total cost of ownership.
For example, two buyers may purchase the same vehicle at the same price. One buyer with excellent credit may receive a low-interest auto loan, while another buyer with poor credit may pay thousands more over the loan term due to a higher rate.
A credit score does not just affect approval—it influences the entire financing structure.
The Main Factors Lenders Evaluate Alongside Credit Scores
Although credit score plays a major role, lenders usually consider multiple financial factors:
- Payment history: Whether previous bills and loans were paid on time
- Credit utilization: How much available credit is currently being used relative to your total limit (financial experts often recommend keeping this ratio well below 30%). For a deeper understanding of how these scoring components work together, you can read the breakdown on Forbes Advisor’s guide to credit scores.
- Length of credit history: How long accounts have been active
- Credit mix: Variety of credit accounts, such as loans and credit cards
- Recent credit applications: Number of recent inquiries
- Income stability: Ability to handle monthly payments
A strong credit score combined with stable income creates a stronger auto finance application.
Auto Finance Credit Score Categories and Expected Loan Terms
Credit scoring models vary, but lenders commonly divide borrowers into general credit categories. These categories help determine financing risk and possible loan conditions.
| Credit Score Range | Typical Credit Category | Auto Finance Expectations | Common Challenges |
|---|---|---|---|
| 750+ | Excellent Credit | Lowest interest rates, flexible terms, strong approval chances | Limited challenges; lenders compete for borrowers |
| 700–749 | Good Credit | Competitive rates and favorable loan options | Slightly higher rates than top-tier borrowers |
| 650–699 | Fair Credit | Approval possible with moderate rates | Higher interest costs and stricter review |
| 600–649 | Poor Credit | Limited lender options and higher APRs | Larger down payments may be required |
| Below 600 | Subprime Credit | Specialized financing options | Very high rates and stricter conditions |
These ranges are general guidelines. Every lender uses its own approval criteria, and other financial factors can influence the final decision.
Real-World Example: How Credit Score Changes the Cost of Auto Finance
A credit score does not only affect whether you get approved for an auto loan — it directly impacts your monthly payment, interest rate, and the total amount you pay over the life of the loan.
Let’s assume a borrower takes a $10,000 auto loan with a repayment period of 5 years (60 months). Depending on the borrower’s credit score, the interest rate offered by the lender can vary significantly, creating a major difference in the overall loan cost.
| Credit Score Category | Estimated Interest Rate | Monthly Payment (Approx.) | Total Repayment | Total Interest Paid |
|---|---|---|---|---|
| Excellent Credit (750+) | 5% APR | ~$189/month | ~$11,323 | ~$1,323 |
| Good Credit (700–749) | 7% APR | ~$198/month | ~$11,880 | ~$1,880 |
| Fair Credit (650–699) | 12% APR | ~$222/month | ~$13,315 | ~$3,315 |
| Poor Credit (600–649) | 18% APR | ~$254/month | ~$15,260 | ~$5,260 |
| Subprime Credit (Below 600) | 24% APR | ~$287/month | ~$17,220 | ~$7,220 |
What Does This Example Show?
- The difference between an excellent-credit borrower and a poor-credit borrower can exceed $4,000 in additional interest costs over the life of the loan.
- A borrower with poor credit may pay around $65–$100 more per month compared with someone who has excellent credit.
- As the loan amount increases to $20,000 or $30,000, the financial impact of a lower credit score becomes even greater.
Small Credit Improvements Can Create Big Savings
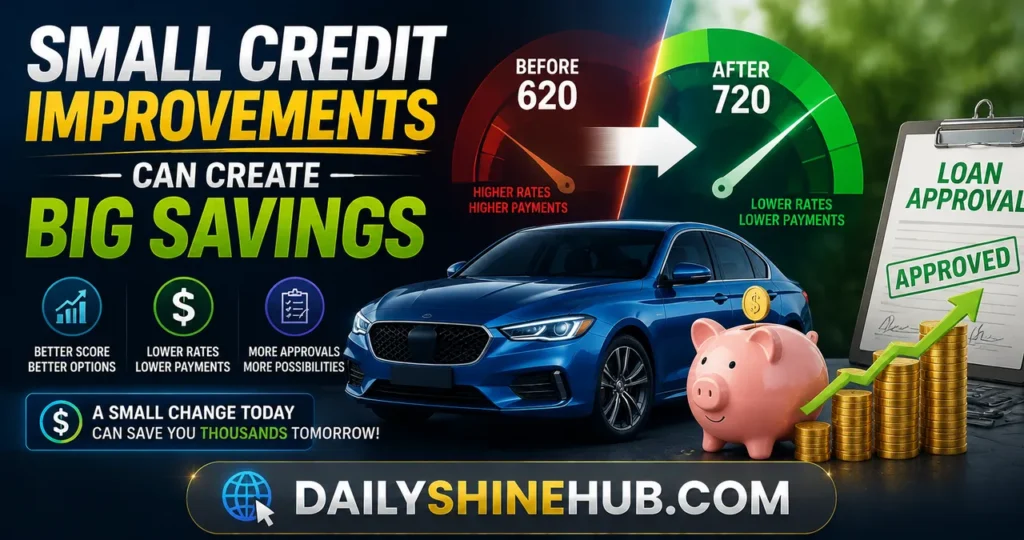
A borrower with a credit score of 630 may still qualify for auto finance, but improving that score closer to 700 can help unlock better interest rates and more affordable loan terms.
Even small improvements in credit habits can create long-term savings.
Simple Ways to Improve Your Credit Score:
- Reduce credit card balances to lower your credit utilization ratio.
- Pay all bills on time to build a stronger payment history.
- Avoid closing old credit accounts unnecessarily, as they may help maintain a longer credit history.
- Limit new loan and credit applications before applying for auto finance.
- Review your credit report regularly and dispute any inaccurate information.
Example: How Better Credit Can Reduce Auto Loan Costs
Imagine a buyer applies for:
- $25,000 auto loan
- 60-month repayment term
- Poor credit interest rate: 18% APR
With a high-risk credit profile, the borrower may end up paying a significantly higher amount in interest.
However, if the same borrower improves their credit score and qualifies for:
- Good credit interest rate: 7% APR
they could save thousands of dollars over the duration of the loan.
This shows why improving your credit score before applying for auto finance can be one of the most effective ways to reduce borrowing costs.
Why Checking Your Credit Score Before Car Shopping Matters
Checking your credit score before visiting a dealership is a smart financial decision because:
- You understand which interest rate range you may qualify for.
- You can identify unfair or unrealistic loan offers.
- You have stronger negotiating power with lenders and dealerships.
- You can create a more accurate monthly car budget.
Bottom Line: In auto finance, your credit score works like a hidden pricing factor. Two buyers can purchase the same vehicle at the same price, but their credit scores can cause a difference of thousands of dollars in total financing costs. Understanding your credit position before applying for a loan can help you secure better terms and make a smarter vehicle purchase decision.
How Excellent Credit Helps You Secure Better Auto Finance Deals
Borrowers with excellent credit usually have the strongest position when negotiating vehicle financing. Lenders view these applicants as reliable customers who are more likely to make payments consistently.
Benefits of Having a High Credit Score When Financing a Car
A high credit score can provide several advantages:
Lower Interest Rates
Interest rates have one of the biggest impacts on the total cost of an auto loan. Even a small difference in APR can create significant savings over several years.
For example, a borrower receiving a low rate on a five-year loan may save thousands compared with someone receiving a high-risk financing rate.
Better Negotiating Power
Buyers with strong credit can compare offers from multiple banks, credit unions, and dealership financing departments. Since they are attractive customers, lenders may compete to provide better terms.
More Flexible Loan Options
Excellent-credit borrowers often qualify for:
- Longer or shorter repayment periods
- Higher loan amounts
- Manufacturer promotional financing
- Lower fees
This flexibility allows buyers to choose financing that matches their financial goals.
Auto Finance Options for Buyers With Good or Average Credit
Not everyone has perfect credit, but borrowers with average credit can still find reasonable auto finance solutions.
A fair credit score does not automatically prevent approval. Many lenders work with borrowers who have moderate credit histories, especially when other financial factors are positive.
How Average Credit Borrowers Can Improve Their Loan Offers
Consumers with mid-range credit scores can strengthen their applications by:
Saving for a Larger Down Payment
A larger down payment reduces the amount borrowed and lowers lender risk. It may also improve approval chances and reduce monthly payments.
Choosing an Affordable Vehicle
Borrowing less money makes the loan easier to manage. Selecting a reliable used vehicle instead of an expensive new model may improve financing approval.
Comparing Multiple Lenders
Different lenders have different risk standards. A bank, credit union, online lender, and dealership may offer different rates for the same borrower.
Adding a Qualified Co-Signer
A co-signer with strong credit may help improve approval chances, although both parties become responsible for repayment.
Auto Finance Challenges for Low Credit Score Borrowers
A low credit score does not mean car ownership is impossible, but it can make financing more expensive.
Why Bad Credit Leads to Higher Auto Loan Costs
Lenders consider borrowers with poor credit higher risk because past financial difficulties may indicate a greater chance of missed payments. To reduce that risk, lenders often charge higher interest rates.
This can result in:
- Increased monthly payments
- Higher total interest costs
- Larger down payment requirements
- Fewer vehicle choices
Steps to Improve Auto Finance Approval With Poor Credit
Borrowers with low credit scores can take several steps before applying:
Review Your Credit Report
Checking your credit report helps identify:
- Incorrect information
- Old debts
- Unpaid accounts
- Reporting errors
Correcting mistakes and resolving major reporting disputes can sometimes require professional guidance; in complex financial disputes, consulting a qualified finance lawyer can help protect your consumer rights. Correcting these mistakes will ultimately improve your credit profile.
Reduce Existing Debt
Lower credit card balances and fewer outstanding obligations can improve your financial appearance.
Avoid Multiple Credit Applications
Applying for several loans at once may create multiple hard inquiries, which can negatively affect credit scores.
Consider a Shorter Loan Term
Although monthly payments may be higher, shorter loans usually reduce total interest costs and show responsible borrowing behavior.
How Dealerships Use Credit Scores in Auto Financing
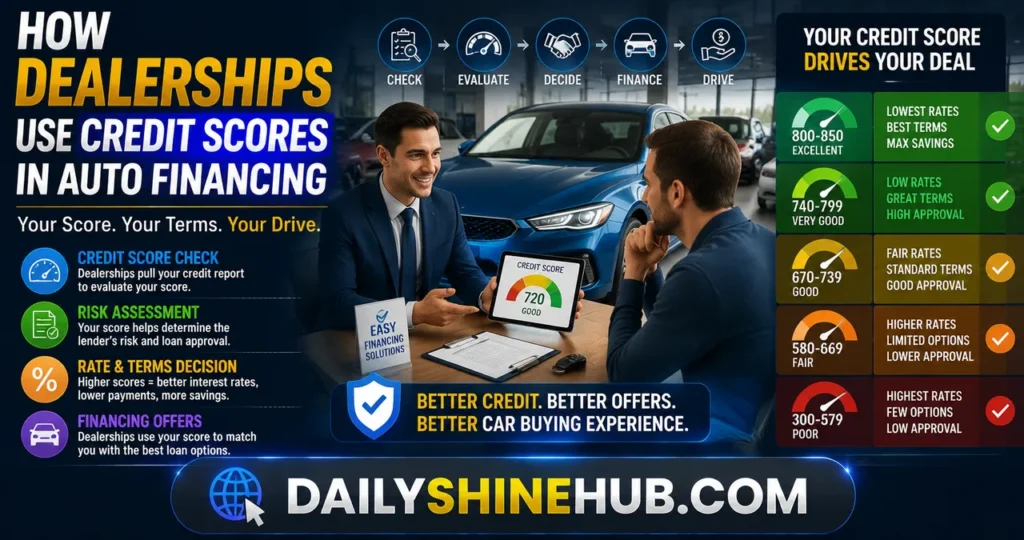
Many dealerships offer financing services, allowing customers to apply for loans directly while purchasing a vehicle. During the application process, dealerships typically collect financial information and send applications to multiple lending partners.
Dealer Financing vs Direct Lending
Car buyers often choose between:
Dealer Financing
- Convenient application process
- Multiple lender options
- Potential promotional offers
- Possible dealer-added fees
Direct Lending
- Apply through a bank or credit union
- May provide competitive rates
- Allows buyers to know financing terms before shopping
Comparing both options can help borrowers find better deals based on their credit profile.
Improving Your Credit Score Before Applying for Auto Finance
A better credit score can lead to significant savings. Buyers who are not in a hurry may benefit from improving their credit before taking out a vehicle loan.
Practical Credit Improvement Strategies
Pay Bills on Time
Payment history is one of the most important parts of credit scoring. Consistent on-time payments build a stronger credit profile.
Keep Credit Card Balances Low
Using a smaller percentage of available credit can improve credit utilization.
Maintain Older Accounts
Long-standing accounts can contribute positively to credit history length.
Limit New Borrowing
Taking on unnecessary debt before applying for auto finance may reduce approval chances.
How Long Does Credit Improvement Take?
Credit improvement timelines vary depending on the borrower’s situation. Some changes may appear within a few months, while rebuilding damaged credit can take longer.
The key is maintaining consistent financial habits over time.
Common Auto Finance Mistakes Related to Credit Scores
Many borrowers make avoidable mistakes that increase financing costs.
Focusing Only on Monthly Payments
A low monthly payment may seem attractive, but extending the loan term can increase total interest paid.
Accepting the First Loan Offer
The first financing option is not always the best. Comparing lenders can reveal better rates.
Ignoring Credit Before Car Shopping
Checking your credit score before visiting dealerships helps you understand your financial position and avoid surprises.
Borrowing More Than You Can Afford
A lender approval does not always mean the loan fits comfortably within your budget.
The Future of Credit-Based Auto Finance Decisions
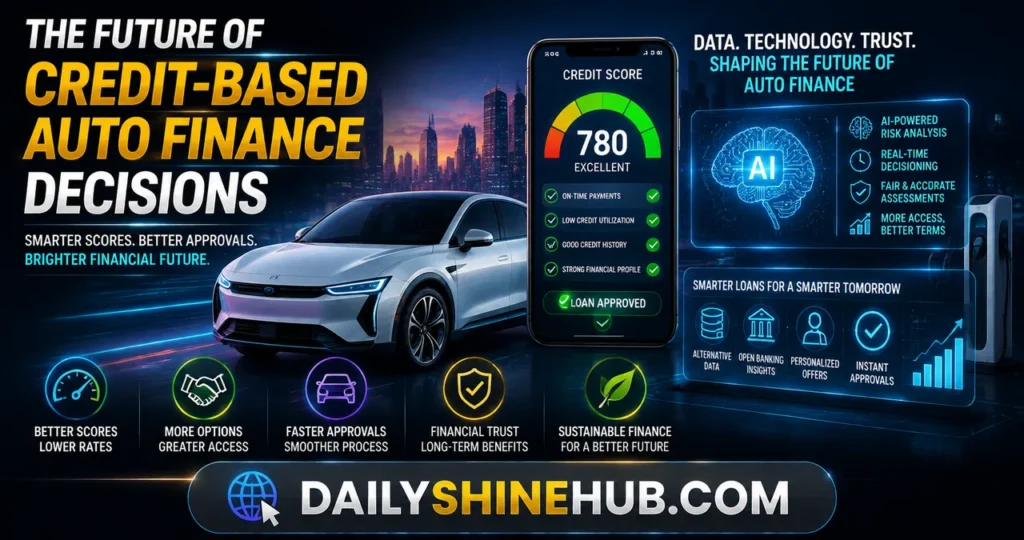
Technology continues to change how lenders evaluate borrowers. Many financial institutions now use automated systems, digital applications, and advanced risk analysis tools to make faster lending decisions.
However, credit scores remain one of the most important indicators in auto finance because they provide a standardized way to measure borrowing behavior.
As financing becomes more personalized, consumers with strong financial habits will continue to benefit from better loan opportunities.
Final Thoughts: Using Your Credit Score as an Auto Finance Advantage
Your credit score is more than just a number—it is a financial tool that directly affects your ability to purchase and finance a vehicle. Understanding how lenders use credit information allows you to prepare before applying, negotiate better terms, and avoid unnecessary costs.
Whether you have excellent credit, average credit, or a challenging credit history, the right strategy can improve your chances of securing suitable auto finance. Reviewing your credit profile, comparing lenders, choosing an affordable vehicle, and maintaining responsible financial habits are essential steps toward successful car financing.
FAQs About Credit Score-Based Auto Finance
1. What credit score is needed for auto finance approval?
There is no single minimum credit score required for auto finance because lenders have different requirements. However, higher scores generally improve approval chances and help borrowers receive lower interest rates.
2. Can I get auto finance with a low credit score?
Yes, borrowers with low credit scores may still qualify through specialized lenders, dealerships, or subprime financing programs. However, they may face higher interest rates and stricter loan conditions.
3. How much can a credit score affect my car loan interest rate?
A credit score can significantly influence the interest rate offered. Borrowers with strong credit typically receive lower rates, while lower-credit borrowers may pay more due to increased lender risk.
4. Should I improve my credit score before applying for auto finance?
If purchasing a vehicle is not urgent, improving your credit score before applying may help you qualify for better rates and reduce long-term financing costs.
5. Do lenders only consider credit scores for auto loans?
No. Lenders also evaluate income, employment stability, debt obligations, down payment amount, loan term, and vehicle value when making auto finance decisions.
Ethan Shine is a passionate content strategist, tech enthusiast, and digital media contributor at DailyShineHub. With over 5 years of experience in blogging and search engine optimization, Ethan specializes in breaking down complex topics into clear, actionable insights. When he isn’t researching the latest industry trends, he enjoys exploring global news, digital tools, and modern lifestyle concepts.