Unexpected home damage can quickly become one of the largest unplanned expenses a homeowner faces. Whether the damage is caused by water leaks, storms, fire, mold, or structural issues, one of the first questions most people ask is: How much will this cost?
If you’re a homeowner trying to estimate repair expenses, prioritize projects, and avoid financial surprises, this guide is designed specifically for you. Instead of focusing on repair techniques, we’ll explore how to build a realistic repair budget, understand cost drivers, compare contractor estimates, and prepare financially for home restoration.
Why Accurate Cost Estimation Matters Before Starting Repairs
Many homeowners make the mistake of approving repairs before understanding the full financial picture. While acting quickly is important—especially after emergencies—rushing into contracts can lead to budget overruns.
A detailed cost estimate helps you:
- Prevent unexpected expenses
- Compare contractor bids fairly
- Prioritize urgent versus cosmetic repairs
- Negotiate confidently
- Plan financing if needed
- Maximize insurance reimbursements where applicable
Even if your insurance covers part of the damage, understanding actual repair costs allows you to identify coverage gaps and avoid paying more than necessary.
The Biggest Factors That Influence Home Damage Repair Costs
No two repair projects cost exactly the same. Several variables determine your final bill.
Type of Damage
Different forms of damage require different specialists, materials, and repair methods.
Common examples include:
- Water damage
- Fire and smoke damage
- Wind or storm damage
- Foundation damage
- Roof damage
- Mold remediation
- Electrical damage
- Plumbing failures
Structural damage generally costs significantly more than cosmetic repairs because it often involves engineering evaluations and building permits.
Extent of the Damage
Minor drywall replacement may only affect one room, while hidden moisture behind walls can require demolition, drying equipment, insulation replacement, and reconstruction.
The larger the affected area, the higher the labor and material costs.
Age of the Home
Older homes often require additional work because contractors may discover:
- Outdated electrical wiring
- Aging plumbing
- Asbestos-containing materials
- Lead-based paint
- Structural deterioration
These issues can increase labor time and regulatory compliance costs.
Local Labor Rates
Repair costs vary widely depending on your location. Metropolitan areas typically have higher labor charges than rural communities due to demand and operating costs.
Building a Realistic Home Repair Budget
Creating a repair budget involves more than adding contractor estimates together.
A well-planned budget includes every stage of the restoration process. Homeowners can also use a digital spreadsheet to organize contractor quotes, material costs, permits, and contingency funds in one place. Google Sheets can be useful for creating and updating a repair budget as project costs change.
Step 1: Identify Immediate Safety Repairs
Prioritize repairs that affect:
- Structural stability
- Electrical hazards
- Water intrusion
- Gas leaks
- Fire hazards
These repairs should receive funding before cosmetic improvements.
Step 2: Separate Essential and Optional Repairs
Ask yourself:
Essential repairs
- Roof replacement
- Foundation stabilization
- Plumbing repairs
- Electrical corrections
- Water damage restoration
Optional improvements
- Cabinet upgrades
- New flooring styles
- Paint color changes
- Decorative lighting
- Landscaping enhancements
Separating these categories helps control spending.
Step 3: Include Hidden Costs
Many homeowners underestimate expenses because they forget indirect costs.
Examples include:
- Building permits
- Engineering inspections
- Dumpster rental
- Temporary housing
- Storage units
- Professional cleaning
- Landscaping restoration
Adding these items early creates a more realistic financial plan.
Typical Repair Cost Categories
The following table provides a general overview of common repair categories and budgeting considerations.
| Repair Category | Typical Budget Consideration | Major Cost Drivers |
|---|---|---|
| Water Damage | Moderate to High | Drying equipment, mold prevention, drywall replacement |
| Roof Repairs | Moderate to High | Roofing material, roof size, accessibility |
| Fire Damage | High | Smoke cleanup, reconstruction, electrical work |
| Foundation Repairs | High | Structural stabilization, engineering, excavation |
| Mold Remediation | Moderate to High | Contaminated area size, testing, containment procedures |
| Plumbing Repairs | Low to High | Pipe location, water damage, replacement materials |
| Electrical Repairs | Moderate | Code upgrades, rewiring, inspections |
| Interior Finishing | Low to Moderate | Paint, flooring, trim, labor quality |
These ranges vary significantly depending on property size, regional pricing, and project complexity.
How to Compare Contractor Estimates Effectively
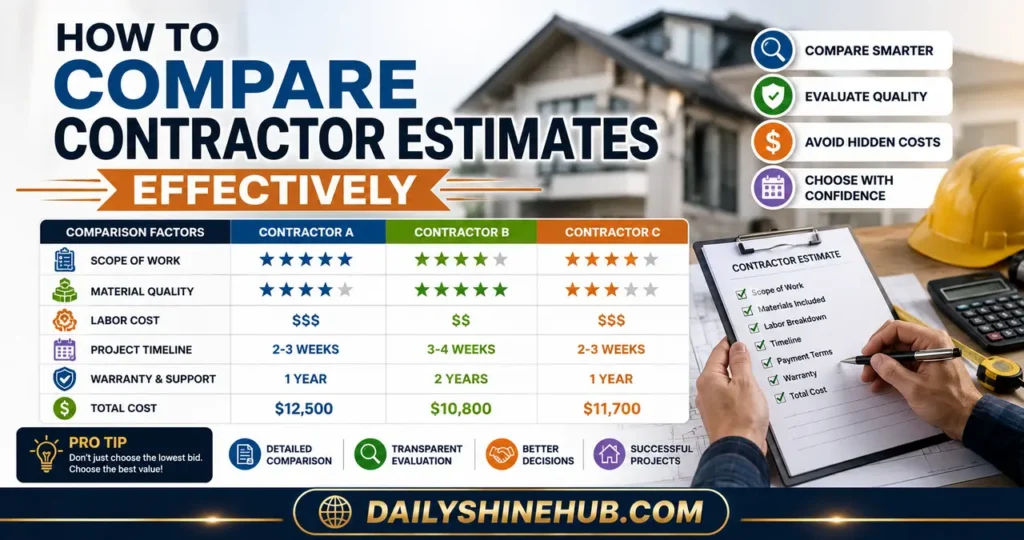
Receiving multiple estimates is one of the smartest budgeting strategies.
However, choosing the lowest price isn’t always the best decision.
Instead, compare estimates based on:
Scope of Work
Every estimate should clearly explain:
- Materials included
- Labor hours
- Demolition work
- Cleanup
- Waste disposal
- Permit responsibilities
- Warranty coverage
A lower estimate may exclude important services.
Material Quality
Two contractors may quote similar repairs using very different materials.
Higher-quality materials often provide:
- Longer lifespan
- Better warranties
- Lower maintenance costs
- Greater resale value
Timeline
Longer repair schedules may increase indirect costs such as hotel stays or rental housing.
A slightly higher quote with faster completion may save money overall.
Planning for Unexpected Expenses
Nearly every major repair project encounters surprises.
Contractors may discover:
- Hidden mold
- Rotting framing
- Pest damage
- Electrical code violations
- Foundation cracks
- Damaged insulation
Because of this uncertainty, experts often recommend setting aside a contingency fund.
A contingency reserve of 10% to 20% of your projected repair budget can help absorb unforeseen expenses without disrupting the project.
For example:
If your repair estimate is $25,000, budgeting an additional $2,500 to $5,000 provides valuable financial flexibility.
Insurance and Budget Planning
Insurance can reduce repair costs, but homeowners should understand what is and isn’t covered.
Generally, policies may cover sudden and accidental events such as:
- Burst pipes
- Storm damage
- Fire
- Wind damage
- Falling trees
However, insurers often exclude damage caused by:
- Deferred maintenance
- Gradual leaks
- Wear and tear
- Pest infestations
Review your deductible before calculating your personal budget.
Even approved claims often require homeowners to cover deductible amounts plus any upgrades beyond original materials.
Financing Options for Major Home Repairs
Large repair bills don’t always have to be paid from savings.
Depending on your situation, financing options may include home equity loans, HELOCs, personal loans, or emergency savings. For homeowners dealing with complicated financing agreements or legal questions related to borrowing, consulting a finance lawyer may provide additional guidance before signing a major agreement.
Home Equity Loans
These often provide lower interest rates for homeowners with substantial equity.
They work well for major structural repairs.
Home Equity Lines of Credit (HELOC)
A HELOC offers flexible borrowing for projects completed in phases.
You only borrow what you need.
Personal Loans
Personal loans may be suitable for moderate repair projects when home equity financing isn’t available.
Interest rates typically depend on credit history.
Emergency Savings
If available, emergency funds help avoid financing costs altogether.
However, avoid depleting all savings without leaving funds for future emergencies.
Budgeting Mistakes Homeowners Should Avoid
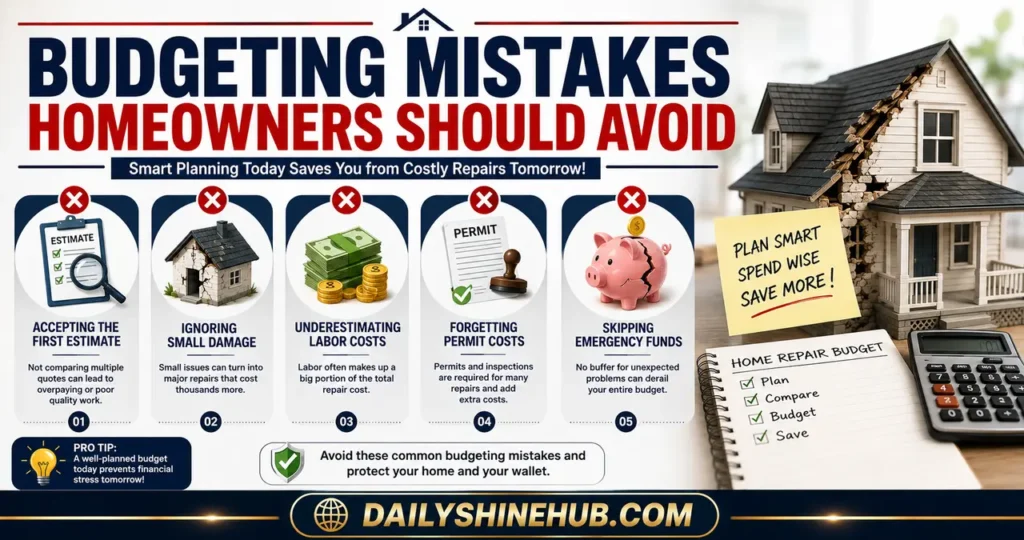
Even careful homeowners sometimes make costly financial mistakes.
Common examples include:
Accepting the First Estimate
Obtain at least three detailed quotes whenever possible.
Comparing multiple contractors helps identify unusually high or suspiciously low pricing.
Ignoring Small Damage
Minor water stains, roof leaks, or foundation cracks can become expensive structural repairs if delayed.
Early intervention often saves thousands of dollars.
Underestimating Labor Costs
Material prices are only part of the budget.
Labor frequently represents a significant portion of total repair expenses, especially for specialized trades.
Forgetting Permit Costs
Many structural, electrical, and plumbing repairs require permits and inspections.
These fees should be included in your financial planning.
Skipping Emergency Funds
Unexpected discoveries are common during demolition.
Without contingency funds, projects may stall midway.
Long-Term Budgeting After Repairs
Once repairs are complete, homeowners should shift focus toward preventing future damage.
Building a maintenance budget reduces the likelihood of expensive emergency repairs.
Consider scheduling regular inspections for:
- Roofing
- HVAC systems
- Plumbing
- Gutters
- Foundation drainage
- Exterior siding
- Windows and doors
Routine maintenance typically costs far less than emergency restoration.
Setting aside a small monthly amount for future repairs creates a financial cushion and extends the life of your home’s major systems.
Final Thoughts
Home damage repair is about more than fixing what’s broken—it’s about making informed financial decisions that protect your property and your long-term budget. By understanding the factors that influence repair costs, comparing contractor estimates carefully, accounting for hidden expenses, and maintaining a contingency fund, homeowners can approach restoration projects with greater confidence.
A well-prepared budget not only reduces financial stress but also helps ensure repairs are completed safely, efficiently, and to a high standard. Whether you’re addressing a minor leak or recovering from significant storm damage, thoughtful planning is one of the most valuable tools you can bring to the repair process.
FAQs
1. How many contractor estimates should I get before approving repairs?
It’s generally recommended to obtain at least three detailed estimates. Comparing multiple bids helps you evaluate pricing, scope of work, material quality, and contractor experience before making a decision.
2. How much extra should I budget for unexpected repair costs?
A contingency fund of 10% to 20% of the estimated repair cost is a common guideline. This helps cover hidden damage or unforeseen issues discovered during the project.
3. Does homeowners insurance cover all repair costs?
Not always. Coverage depends on the cause of the damage and your policy terms. Deductibles, exclusions, and coverage limits may leave you responsible for part of the expense.
4. Is it better to repair damage immediately or wait until I have more money?
Safety-related and damage-spreading issues—such as leaks, structural problems, or electrical hazards—should be addressed immediately. Delaying these repairs often leads to higher costs later.
5. What’s the biggest budgeting mistake homeowners make during repair projects?
One of the most common mistakes is budgeting only for the contractor’s quote while overlooking permits, inspections, temporary accommodations, cleanup, and unexpected repairs. A comprehensive budget provides a much more accurate picture of total project costs.
Ethan Shine is a passionate content strategist, tech enthusiast, and digital media contributor at DailyShineHub. With over 5 years of experience in blogging and search engine optimization, Ethan specializes in breaking down complex topics into clear, actionable insights. When he isn’t researching the latest industry trends, he enjoys exploring global news, digital tools, and modern lifestyle concepts.