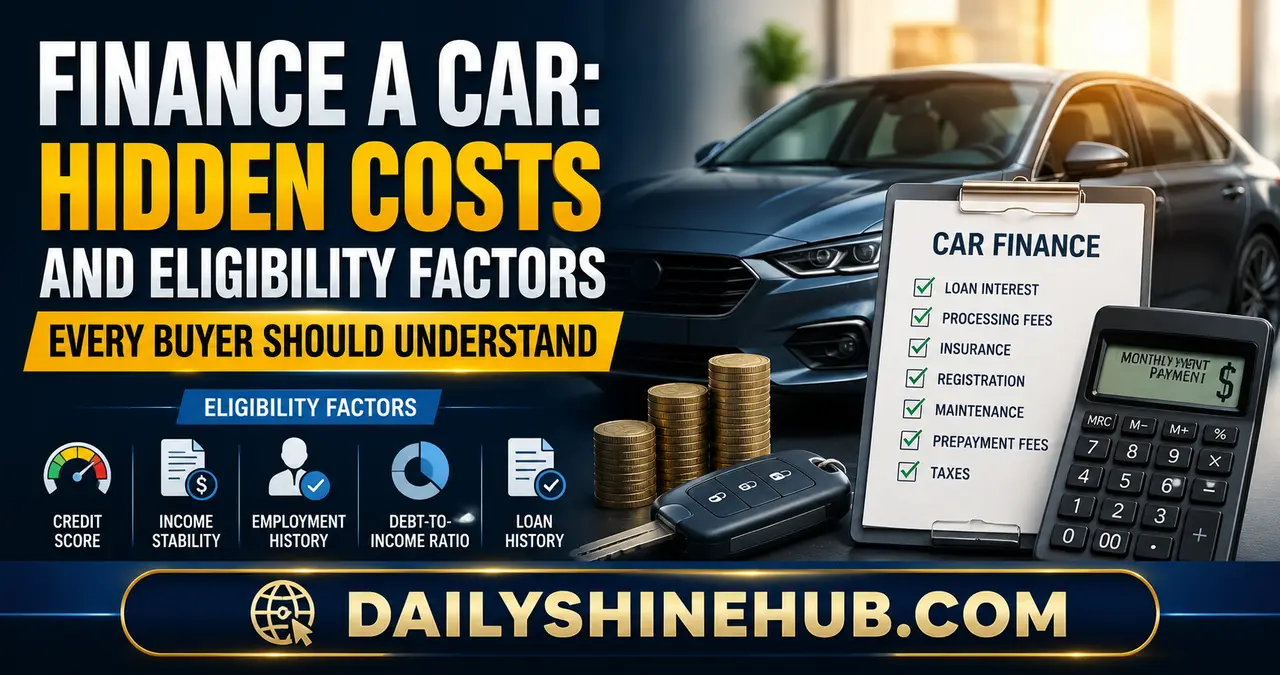
Buying a car is one of the biggest financial decisions many people make, and financing often appears to be the easiest way to make ownership affordable. Instead of paying the entire vehicle price upfront, car finance allows buyers to spread payments over months or years. However, many buyers focus only on the advertised monthly payment and overlook the hidden costs, eligibility requirements, and long-term financial impact of a car loan. Understanding these factors before signing a finance agreement can help you avoid unexpected expenses and choose a loan that fits your financial situation. This guide is designed for buyers who want to finance a car while paying close attention to approval requirements, extra charges, and the real cost of vehicle ownership. For a broader look at vehicle-related financing options, you can also explore this guide to auto finance.
Understanding Car Finance Beyond the Monthly Payment
When shoppers visit a dealership or apply online for vehicle financing, they often see attractive offers based on low monthly payments. While a smaller monthly payment can make a car seem affordable, it does not always represent the total amount you will pay. A longer loan term may reduce your monthly bill but increase the total interest paid over time.
Buyers researching specific dealership financing processes can also review this detailed guide to Subaru finance to understand how vehicle credit applications and financing decisions typically work.
Car financing involves borrowing money from a lender to purchase a vehicle. The borrower then repays the loan through scheduled payments that include the principal amount and interest charges. The final cost depends on several factors, including the vehicle price, loan term, credit score, interest rate, down payment, and additional fees.
A financially responsible buyer should evaluate the complete cost of financing instead of focusing only on whether the monthly payment fits their budget.
This same principle applies to specialized equipment purchases, where businesses may use crane finance to spread the cost of expensive machinery over time.
Why Eligibility Matters Before Applying for Car Finance
Before approving a car loan, lenders evaluate whether an applicant can realistically repay the borrowed amount. Eligibility requirements vary between lenders, but most financial institutions review similar factors.
Credit Score Requirements
Your credit score is one of the most important factors affecting car finance approval. A strong credit history usually helps borrowers qualify for lower interest rates, while a poor credit score may result in higher rates or stricter loan conditions.
Lenders examine your previous borrowing behavior, including:
- Payment history
- Outstanding debts
- Credit card balances
- Length of credit history
- Recent credit applications
A higher credit score can significantly reduce the overall cost of financing because lower interest rates mean less money paid toward interest.
Income and Employment Stability
Lenders want proof that you have a reliable source of income to handle monthly payments. Many finance providers ask for employment details, salary information, or business income records.
Stable employment can improve approval chances because it demonstrates financial consistency. Applicants with irregular income may need additional documentation or a larger down payment to qualify.
Debt-to-Income Ratio
Your debt-to-income ratio compares your monthly debt obligations with your income. This helps lenders determine whether taking on a new car loan would create financial pressure.
For example, someone with high credit card balances, personal loans, and other financial commitments may have difficulty qualifying for additional financing.
Down Payment Amount
A larger down payment reduces the amount you need to borrow. This can improve approval chances and lower monthly payments.
A smaller loan amount also means:
- Less interest paid over time
- Lower monthly financial pressure
- Reduced risk of owing more than the vehicle is worth
Many buyers underestimate how much a down payment can influence their financing options.
Hidden Costs When You Finance a Car
The advertised vehicle price is rarely the final amount you pay. Several additional expenses can increase the real cost of financing.
| Hidden Cost | How It Affects Your Car Finance Budget | Common Mistake Buyers Make |
|---|---|---|
| Interest Charges | Increases the total repayment amount over the loan period | Focusing only on monthly payments |
| Loan Fees | Adds extra upfront or ongoing costs | Ignoring lender paperwork charges |
| Insurance Premiums | Increases monthly ownership expenses | Forgetting insurance requirements |
| Maintenance Costs | Creates additional long-term expenses | Budgeting only for loan payments |
| Registration and Taxes | Raises the total purchase cost | Assuming vehicle price includes everything |
| Early Repayment Fees | May create charges for paying off the loan early | Not reading loan terms carefully |
Interest Rates: The Cost Many Buyers Underestimate
Interest is one of the biggest hidden expenses in car financing. Even a small difference in interest rates can change the total amount paid over several years.
For example, two buyers may purchase the same vehicle but pay different amounts because one qualifies for a lower interest rate. Borrowers with strong credit profiles often receive better financing offers, while higher-risk borrowers may pay significantly more.
Factors that influence interest rates include:
- Credit score
- Loan duration
- Vehicle age
- Loan amount
- Current market conditions
- Lender policies
Before accepting a finance offer, compare the annual percentage rate (APR), not just the monthly payment.
Longer Loan Terms: Lower Payments With Higher Costs
Many dealerships promote longer repayment periods because they make monthly payments appear more affordable. However, extending a loan from three years to six or seven years can increase the amount of interest paid.
A longer loan term may create problems such as:
- Paying more for the vehicle than its actual value
- Having less financial flexibility
- Remaining in debt for many years
- Difficulty selling or trading the vehicle
Buyers should choose the shortest loan term they can comfortably afford without creating financial stress.
Dealership Financing vs Bank or Online Lenders
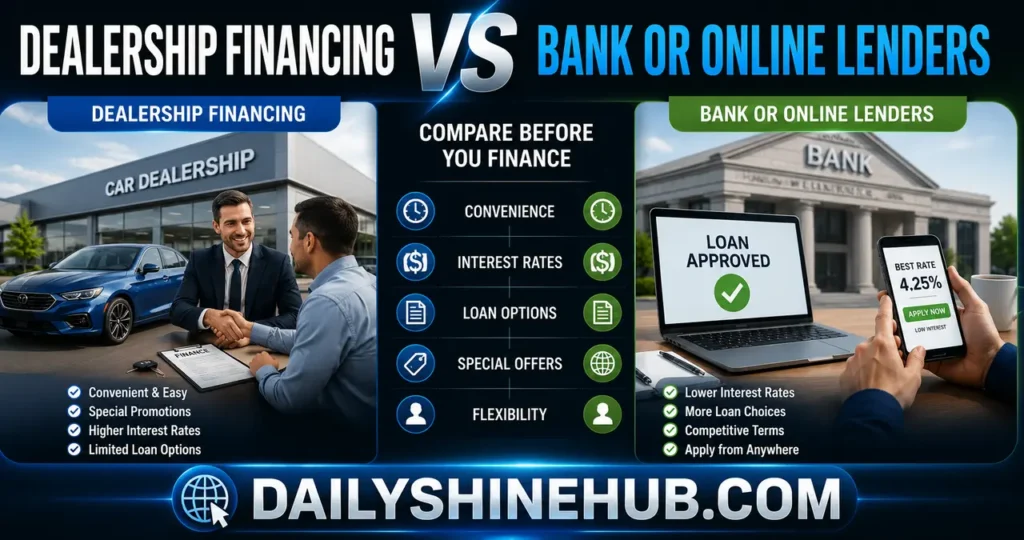
Car buyers often have multiple financing options. Understanding the differences can help you find better terms.
Dealership Financing
Many dealerships offer financing directly through partnerships with banks and finance companies. This option is convenient because buyers can complete the vehicle purchase and loan process in one location.
Advantages include:
- Faster approval process
- Special promotional offers
- Convenient paperwork handling
- Potential manufacturer incentives
However, dealership financing may sometimes include additional products or fees that increase the total loan cost.
Bank Financing
Banks and credit unions often provide auto loans with competitive interest rates, especially for customers with strong financial profiles.
Benefits include:
- Clear loan terms
- Possible lower interest rates
- Direct relationship with the lender
Getting pre-approved before visiting a dealership can also strengthen your negotiating position.
Online Car Finance Providers
Online lenders allow buyers to compare offers quickly and apply digitally. They may provide flexible options, but borrowers should carefully review fees and repayment conditions.
Digital financial services continue to evolve as technology changes how consumers compare, apply for, and manage financial products. For readers interested in the broader technology side of modern financial services, IBM provides an overview of how fintech is transforming financial services through digital technologies.
Vehicles increasingly rely on connected systems, digital displays, driver-assistance features, and other technology, making technology considerations another part of modern vehicle ownership. Buyers researching technology-related products and innovations can explore Daily Shine Hub’s coverage of gizmo and gadgets for additional context on consumer technology trends.
Additional Expenses After Financing Approval
Getting approved for a car loan is only the beginning of your financial responsibility. Vehicle ownership includes several ongoing expenses.
Insurance Requirements
Most lenders require comprehensive insurance coverage because the vehicle acts as collateral for the loan. Insurance costs depend on factors such as:
- Driver history
- Vehicle model
- Location
- Coverage level
- Age of the vehicle
A buyer should calculate insurance costs before deciding how much car they can afford.
Maintenance and Repairs
A financed vehicle still requires regular maintenance. Oil changes, tires, brakes, inspections, and unexpected repairs can become significant expenses.
Newer vehicles may have lower repair costs initially, while used vehicles may require more frequent maintenance.
Depreciation
Vehicles lose value over time. Depreciation is an important factor because you may owe more on the loan than the car is worth, especially with small down payments and long loan terms.
This situation is known as being “upside down” on a car loan.
Common Eligibility Mistakes That Reduce Approval Chances
Many applicants make avoidable mistakes before applying for vehicle finance.
Applying Without Checking Credit
Submitting multiple loan applications without understanding your credit position can lead to unnecessary credit inquiries. Reviewing your credit report first allows you to correct errors and improve your chances.
Borrowing More Than You Can Afford
Approval does not always mean affordability. A lender may approve a larger loan than what comfortably fits your monthly budget.
Consider your full financial situation, including:
- Housing costs
- Utilities
- Savings goals
- Emergency expenses
- Existing debts
Ignoring Loan Terms
Some buyers sign finance agreements without fully understanding:
- Interest rates
- Fees
- Payment schedules
- Early repayment conditions
- Additional services
Reading the complete contract helps prevent expensive surprises.
How to Improve Your Chances of Getting Approved
If you plan to finance a car, preparing before applying can improve your options.
Improve Your Credit Profile
Simple steps can help strengthen your credit position:
- Pay bills on time
- Reduce credit card balances
- Avoid unnecessary borrowing
- Check credit reports for errors
Save for a Larger Deposit
A larger upfront payment lowers your borrowing requirement and shows lenders that you are financially prepared.
Compare Multiple Finance Offers
Do not accept the first loan offer automatically. Comparing different lenders can help you find better interest rates and repayment conditions.
Prepare Required Documents
Having documents ready can speed up the approval process. Common requirements include:
- Identification documents
- Proof of income
- Employment details
- Address verification
- Banking information
How to Calculate the Real Cost of Financing a Car
Before committing to a loan, calculate the complete ownership cost. This should include:
- Vehicle purchase price
- Down payment
- Interest charges
- Taxes and registration fees
- Insurance
- Maintenance
- Fuel expenses
- Potential repair costs
A realistic budget helps prevent financial difficulties after purchasing the vehicle.
Smart Questions to Ask Before Signing a Car Finance Agreement
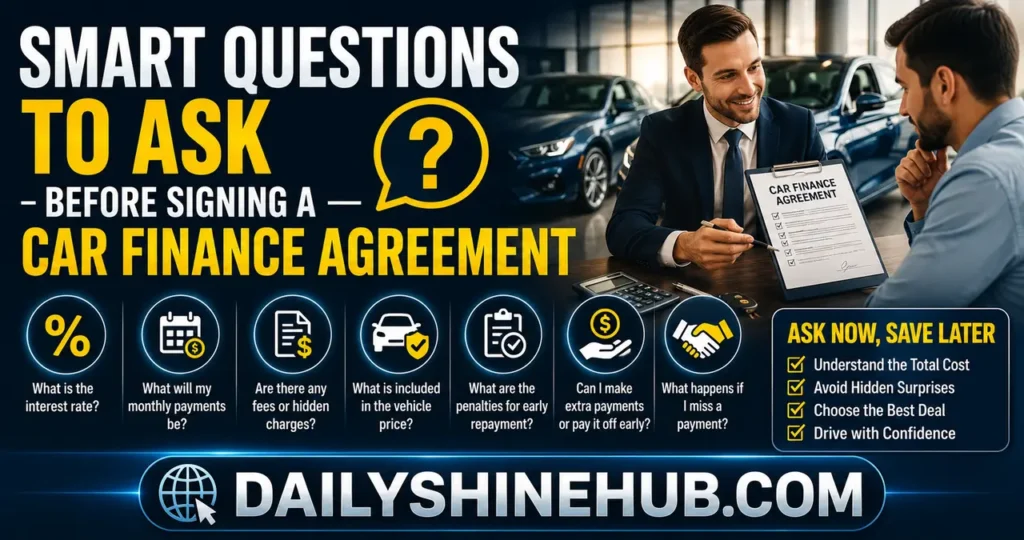
Before finalizing your loan, ask the lender or dealership:
- What is the total repayment amount?
- What is the interest rate and APR?
- Are there additional fees?
- Can I make early payments without penalties?
- What happens if I miss a payment?
- Are optional protection products included?
Getting clear answers can help you avoid costly surprises.
Final Thoughts on Financing a Car With Confidence
Financing a car can be a practical solution for buyers who cannot pay the full purchase price upfront. However, the true cost of a vehicle loan extends beyond the monthly payment. Eligibility requirements, interest rates, fees, insurance, maintenance, and depreciation all affect the overall financial impact.
The best approach is to evaluate your personal financial situation, understand lender requirements, compare multiple offers, and calculate every expense before committing. A carefully planned car finance decision can help you enjoy vehicle ownership without creating unnecessary financial pressure.
FAQs About Hidden Costs and Eligibility When Financing a Car
1. What credit score is needed to finance a car?
The required credit score depends on the lender, but higher scores generally improve approval chances and help borrowers receive lower interest rates. People with lower scores may still qualify but often face higher financing costs.
2. What hidden fees should I look for when financing a car?
Common hidden costs include loan processing fees, documentation charges, taxes, registration costs, insurance requirements, and optional products added to the finance agreement.
3. Does income affect my ability to finance a vehicle?
Yes. Lenders review income stability and debt obligations to determine whether you can manage monthly payments. A consistent income source can improve approval chances.
4. Is a longer car loan term a good idea?
A longer loan term lowers monthly payments but usually increases the total interest paid. Buyers should choose a repayment period that balances affordability with overall cost.
5. Can I finance a car if I have poor credit?
Yes, some lenders offer financing options for borrowers with poor credit. However, these loans often come with higher interest rates, stricter conditions, or requirements such as a larger down payment.
Ethan Shine is a passionate content strategist, tech enthusiast, and digital media contributor at DailyShineHub. With over 5 years of experience in blogging and search engine optimization, Ethan specializes in breaking down complex topics into clear, actionable insights. When he isn’t researching the latest industry trends, he enjoys exploring global news, digital tools, and modern lifestyle concepts.